Translate

Friday, June 4, 2021

Whole Life Insurance, love it !

In year 2021, we spent a good sum of S$23,048.36 for insurance for a household of three.

I want to talk about the beauty of whole life insurance here.

I have fully paid up the whole life insurance for my son as I shorten the payment term to 5 years only. It is a done deal. :)

As for our own whole life insurance plan of 20 years payment, we will fully settle the whole life insurance plans in 5 years time. 

What is the strategy of our whole life insurance plan? It is simple, only 2 options.

Option 1:
We should never surrender the whole life insurance plan. That's insurance, dude!
It is meant to pass on the death benefits sum to your loved one once you are dead. 

Option 2:
If you have no loved one or you want to surrender the plan for future retirement income, you can do so but make sure you surrender the whole life insurance plan as late as possible. How late?

At the age of 55, you can start to withdraw CPF monies as much as you want after setting aside Full Retirement Sum (FRS) to RA (Retirement Account). Hence, you definitely DO NOT WANT to surrender at such age.

From the age of 65, you start to receive CPF LIFE monthly payout until death. 
S$2,000 a month for each of us (FRS sum will be S$250,000 at our age of 55).

From the age 62 to 71, you also start to withdraw monies from your SRS account, spanning 10 years horizon. 

Hence, in my opinion, the best time to surrender the whole life insurance plan is at the age of 72 and above if you really do not want to pass on the death benefits to your loved one. That's fine. 

What's the surrender value ?

My son, at the age of 71, he will receive cash payout of S$444,843.

At my age of 71, I will receive cash payout of S$195,580.

At my wife age of 72, she will receive cash payout of S$150,027.

Me and my wife total payout of S$345,607 is a tidy sum at the age of 71/72. 
Not one cent more, not one cent less. That's Tokio Marine. 

In addition, there is also one Whole Life Insurance from Prudential with a surrender value of S$130,206 at her age of 73. That brings to the total of S$475,813 payout from Whole Life Insurance. 

Why so many people still dislike Whole Life Insurance?

Just because of the phrase "buy term & invest the rest" will eliminate all the goodness above?
I don't think so.

I can always still buy term insurance anytime to boost up the coverage if I want to. 
Invest the rest? I have already done so.

That's my strategy of Whole Life Insurance, love it!


Monday, May 10, 2021

CPF SA shielding ( right before age 55 )

When we talk about CPF SA shielding, it is to be executed right before age 55 and complete the shielding immediately after RA (retirement account) is formed at 55th birthday.

Why?

Year 2021 Full Retirement Sum (FRS) is S$186,000.

When you reach 55th this year, CPF will automatically deduct your SA amount first, e.g. S$186,000 to form RA account. As SA account draws 1.5% interest higher than OA account, you want CPF to deduct the big bulk of money from OA account instead of SA account. Hence, you are doing the CPF SA shielding by leaving minimum requirement of S$40,000 in SA account and move out all the remaining SA balance to buy short term bond (e.g. NIKKO AM SHENTON SHORT TERM BOND FUND). Then, CPF board can only deduct S$40,000 in SA and the remaining balance to be deducted from OA account instead. Once the RA account is formed with S$186,000 (year 2021 FRS figure), you shall immediately sell the bond fund and bring back the cash to SA account and enjoy the 4% interest.

Many people will quote the news article below whenever we talk about CPF SA shielding.


NIKKO AM SHENTON SHORT TERM BOND FUND

During the last year COVID19 pandemic, you can see the short term bond fund actually dropped 2.5% in February 2020 and since then, it had gone up by 4.3%.


For the past 10 years, the short term bond fund only encountered 2 major correction, once in September 2013 and once in Feb 2020. 

Generally, it is still safe if you just park the SA balance in the short term bond fund in less than 1 week time.


6 months before your 55th birthday, CPF will send you a birthday letter (as shown below). That's the letter everyone is waiting for at age of 54 ! :)

It's one good example from my "friend".


For the above example, if you continue to work until age 65, without CPF SA shielding, the projected CPF balance shall be the following:


If you continue to work until age 65, with CPF SA shielding, the projected CPF balance will be:


In this real life example, with CPF SA shielding, you actually can get:
S$12,445 more at the age of 60 or 
S$29,223 more at the age of 65.

Is it worth it? Why not? Free money!

For my own case 14 years later at age 55, with CPF SA shielding, I can get:
S$20,629 more at the age of 60 or 
S$48,438 more at the age of 65.

Friday, April 16, 2021

CPF Regrossed Balances benchmark & CPF Balance Projection (Achieved 1M41 & Target 4M65)

I just realized there is a CPF Annual Report that we can benchmark with.

You may click the shortcut link CPFB | CPF Annual Report .


Hence, I decided to benchmark where we stand among the national data.

Below is the distribution of all CPF members by Regrossed Balances and age group as at 31 December 2019.
CPF Annual Report 2020 will be released very soon.

With the figures tabulated, you can benchmark where you stand today. It is quite interesting.

** CPF Regrossed Balances include amounts withdrawn under Investment, Education, Residential Properties, Non-Residential Properties and Public Housing Schemes as at end of period.

We have achieved 1M41 & targeted 4M65. 

(4M65 includes the RA balance starts with FRS sum of S$282,000 when we are at age 55.)

You can reach 1M even faster if you are not using CPF OA for housing loan.

There is also a 1M65 movement by Mr. Loo to advocate reaching a million dollar as a couple by 65 years old. Of course, he refers to real CPF balance, not CPF Regrossed Balances. 

If you have invested a big bulk of CPF OA in S&P 500 through Endowus, those monies are not counted as real CPF balance (because that will be CPF regrossed balance) but you can get much more returns at the end of the day once you sold the S&P 500 fund if the fund is doing well. Vice versa.


Next is to project the CPF balances (with good estimation) at the age of 55. 
This is an important stage as we shall do CPF SA shielding few days before age 55.

Everyone shall simulate and project his/her own CPF balances with few assumptions mentioned below:
- Considering only total 13 months contribution (that's to include the usual 13th month)
- If you have 1 month bonus or more, the figures will be more!
- The interest simulation only take 2.5% in OA, 4% in SA, the figures shall be more because the first S$60,000 in (OA+SA) will enjoy additional 1% interest.


Last but not least, CPF is just one, just "ONE" pillar of retirement income, just one BASIC only.

For a nice and sound retirement, you still have :
(1) HDB rental income
(2) Private properties (be it Singapore, Malaysia, Australia, UK, etc.).
(3) SRS 
(4) Stocks, US/HK/MY/SG stocks, etc.
(5) Endowus (your S&P500 index , etc. All kind of RoboAdvisor)
(6) Fix deposits, T-bills, bonds, saving bonds.
(7) Endowment, ILP funds, your beloved Cathie Woods ARK fund, ETF , etc. 
(8) You can even surrender your Whole Life Insurance at later age of 65, 70 if you wish to have surrender payout instead of leaving the legacy (death benefits) to your children.
(9) Cash in UOB One, OCBC 360 account, etc.
(10) Crypto like bitcoin, dogecoin !
Wish everyone has a fruitful retirement life!

Tuesday, April 13, 2021

Voluntary Contribution (VC) to CPF MediSave Account (revision 02)

Revision 02 (last paragraph): updated on April 19, 2021

Everyone talks about S$37,740 (Annual Limit).

I finally took the action to max out the voluntary contribution (VC) to MediSave account (MA), with the primary reason as tax relief. It is good to top up by using PayNow because it is done immediately!

I should have done it on January 2, 2021 to enjoy even greater amount of tax relief. I will remember doing that every year in January.

MSL : MediShield
PMI  : Private Medical Insurance
CSL : Careshield Life

All right , this post is for those want to maximize the tax relief if they : 
(1) have not reached the S$80,000 tax relief
(2) have reached FRS of S$186,000 (for year 2021) in CPF SA
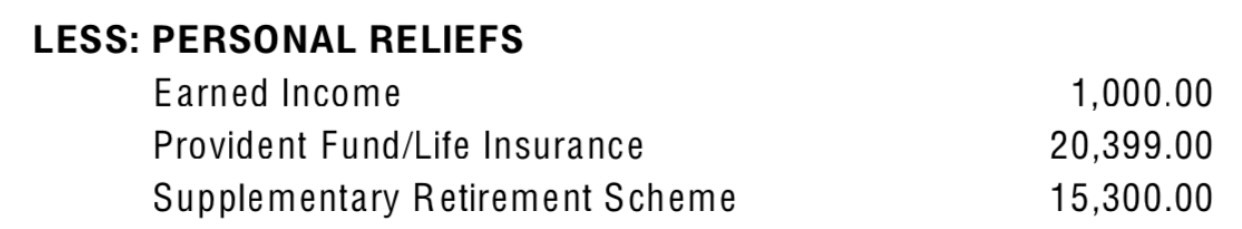
(3) have top up S$15,300 in SRS
(3) have not reached the CPF AL of S$37,740

Why should you do MA top up in January ?

Real example:

(a) Year 2020 :
- BHS in year 2019 was S$57,200 & year 2020 was S$60,000 .

To maximize tax relief:
(1) I should top up MA on Jan 2 , 2020 for S$2,800.
(2) On March 3 , 2020 , I should top up MA for S$610 (after MSL & PMI deduction).
(3) On Dec 16, 2020 , I should top up MA for S$295 (after CSL deduction).

 Total additional tax relief in year 2020 could be : S$2,800 + S$610 + S$295 = S$3,705.


(b) Year 2021:
- BHS 2020 is S$63,000.

To maximize tax relief :
(1) I should top up on Jan 2, 2021 for S$3,000.
(2) Top up S$1,125 on March 16, 2021 (after MSL & PMI deduction).
(3) Top up S$295 on Dec 16, 2021 (after CSL deduction).

Total additional tax relief for year 2021 could be : S$3,000 + S$1,125+ S$295 = S$4,420.

In summary, there are 3 rounds of opportunities to top up in CPF MA, namely:
(1) First week of January after the BHS limit is increased.
(2) After your H&S insurance deduction (for me the deduction is in March annually).
(3) After your CareShield life deduction in December.

You enjoy greater tax savings and at the same time you also prepare more for the future retirement income with compound 4% interest in CPF MA account. Kill two birds with one stone!

Check your CPF Annual Limit balance with the method below.
(1) Log in to your CPF account
(2) Go to my CPF online services
(3) Click on My Requests
(4) Choose Building Up My/ My Recipient's CPF savings
(5) Click on Using Cash > Contribute to my CPF Accounts via PayNow QR or eNETS
(6) Continue the page until you see and click on Check Allowable Contribution.


Revision 02: updated on April 19, 2021
============================

CPF Annual Limit : S$37,740.
(S$102,000 x 37% = S$37,740).

However, the total CPF Relief (maximum) allowed is S$20,400 only (per employment).
S$102,000 x 20% = S$20,400.


I just realized for some years, I have hit the CPF relief of S$20,400, hitting the CPF annual limit of S$37,740 too. Hence, doing the above mentioned voluntary contribution (VC) to MA is possible but you won't enjoy the tax relief. The VC amount that beyond S$37,740 cap will be returned back to you by the end of the year without interest. Just treat it as a good problem.

After all, one shall check in December instead to see if you have hit the CPF annual limit.

From the example above, you will know for those monthly salaries of S$6,000 or more, the Ordinary Wage (OW) will hit the OW ceiling of S$72,000.
(S$6,000 x 12 months = S$72,000).

That left with only S$30,000 for the Additional Wage (AW) ceiling. 
( S$102,000 - S$72,000 = S$30,000 ).

Do take note, the additional wage (AW) includes your:
(1) AWS (13th month) 
(2) Bonuses
(3) En-cash Annual Leave
(4) Etc.


It is possible to burst the CPF Relief (maximum) of S$20,400 if you change the job within a year.

Friday, August 10, 2018

Delaying Monthly CPF LIFE Payouts? (Revision 02)

Revision 02 (last paragraph): updated on November 6, 2019

There is an article talking about delaying monthly CPF LIFE payouts, see below:
https://www.areyouready.sg/YourInfoHub/Pages/News-How-Much-Will-I-Receive-in-Monthly-CPF-LIFE-Payouts.aspx?utm_source=facebook&utm_medium=bc&utm_campaign=bau&utm_content=receive-CPF-LIFE-payouts

FRS will be increased by S$5,000 every year. By the time I reach age 55, the required FRS will be S$256,000. This figure is very close to the CPF illustration of retirement sum of S$256,500.

This is a very good table to show you the monthly payout at age 65, 68 and 70. Let's take the example of retirement sum of S$256,500 at age 55.
Also, take the upper band of the monthly payout at age 65 (S$2,060) , age 68 (S$2,440) and age 70 (S$2,740) for comparison studies.


Comparison table


Delaying Monthly CPF LIFE payouts ?
 
From the comparison table above, the verdict is clear: stick to monthly payout at age 65.
 
I do not see the benefits of delaying. You only start to realize you get more total quantum when you live beyond age 85. S$497,760 compared to S$494,400. And you get S$3,360 more ONLY! Of course if you can live until age 95, the differences will be more. You can get S$48,960 more (if you start the payout at age 68) or S$80,400 more (if you start the payout at age 70). But, we are talking about age 95 ! : (

Hence, my choice is clear. Things that work, don't change.

I am happy to receive S$2,060 per month while it is my turn. Thanks CPF !

Revision 02 (updated on November 6, 2019)
================================

At what age, you will become a burden for CPF board to keep giving you the monthly CPF LIFE payouts?

Age 87 !

Take my case as an example.

By my age of 55, the required RA balance would be S$256,500. It is the perfect match of the illustration above. With Retirement Sum of S$256,500, the monthly payout (at the upper band) would be S$2,060. One year withdrawal from your RA account would be S$2,060 x 12 months = S$24,720.

At the same time, your RA balance continue to attract 4% compound interest.

Hence, the calculation would be:

(1) The RA balance of S$256,500 at age 55 would continue to receive 4% compound interest for 10 years all the way until age 64.

(2) Starting from age 65, we must minus away the yearly withdrawal of S$24,720.

(3) The remaining balance in RA continue to attract 4% compound interest.

With this formula, you will see the RA balance will dry out by the age of 87.

So, age 87 and above will be a burden for CPF Board to continue to issue the monthly CPF LIFE payouts.

If you die early, say age 70, you will have balance of S$297,975 to be distributed to your loved one.


Our CPF at the maximum ...

A Singaporean household of 3. 2 working adults, age 46 (1980s) and 1 young adult age 14. Voluntary Housing Refund (VHR) all monies back to C...