Translate

Monday, January 3, 2022

Rosewood condo sold at all time high price !

My sis was able to sell her condo in November, 2021 at all time high, S$980,000 (the highest price of 3 bedrooms unit at Rosewood). It was S$80,000 above bank valuation.

That's exactly one month before the new property cooling measures announced on December 16, 2021.

It is a 3 bedrooms unit, located at 14th floor, 1,173 sq ft unit at Rosewood condo at Woodlands. Let's see when the next 3 bedrooms unit at Rosewood can be sold above S$980,000. : )


I had stayed at Rosewood for a year in year 2004. Not bad indeed. Good facilities. :)


It was sold at S$835 PSF @ Woodlands!
For 3 bedrooms unit, 1,173 sq ft, there are total 35x transaction for the past 5 years (from January 2017 to January 2022). The details shown in the table below.

For 3 bedrooms unit rental for the past 5 years (from January 2017 to December 2021), there are total 215x records, with the lowest rental S$2,100 and highest rental S$4,000. The median rental is S$2,400 and the average rental is S$2,477.35, pretty close to the median rental of S$2,400!
She bought the unit during the launch in March 2002 at S$552,583 ( S$471PSF ), that's a good profit of S$427,850.
The Rosewood condo had been fully paid. She had used CPF OA monies S$277,505.43 to serve the housing loan and there is an accrued interest of S$91,734.16. After the sales, total of S$369,239.59 will be returned to CPF OA account.
The OA account will be increased from S$3,594.25 to S$372,833.84.
With this, total CPF balance will be S$609,041.85. 
That's 0.61M44 (alone).
Technically speaking, it shall be 0.61M42 (alone) as her last CPF contribution was 3 years ago in August 2019.


I remembered vividly that the property price in Singapore actually crashed between year 2003-2006, you could actually get much cheaper price than the launch price of Rosewood close to S$400K+ for a 3 bedrooms unit. You could have profited even more if you are able to catch the dip. 

By the way, she bought a 5-room HDB flat in year 2006 and rented out Rosewood all the way until year 2021. She did not use CPF OA monies to serve the HDB private bank housing loan. She had also migrated to Sydney three years ago with her family in year 2019 (She works at IT management at Aussie bank). You can imagine the rental collected for 15 years from year 2007 to year 2021, taking average monthly rental of S$2,800 x 12 months x 15 years ~= S$504,000.
With the sale profit of S$427,850, the total profit would be ~= S$931,850. Nice!

In my opinion, if possible, it is always good to purchase at least 1x private property and 1x HDB unit in Singapore. 

The sequence is important now. You have to purchase HDB first then private property, not the other way round anymore as you have to dispose the private property within 6 months after you collect the HDB keys.

Updated on February 14, 2022
============================
The record was broken last month (January 2022), the 3 bedroom unit, 1,173 sq ft, much lower floor (06 to 10) was sold at all-time-high S$993,000. Amazing.

Updated on February 18, 2022
============================
CPF had completed the housing refund, total net amount used S$277,505.43 and total accrued interest S$91,734.16 to CPF OA account.

The CPF OA account now balloon from S$3,594.25 to S$373,603.09.

Total CPF balance now: S$609,811.10. 
Technically speaking, achieved 0.61M42 (alone). 
She has stopped CPF contribution since August 2019. Pretty impressive.

Next task: to perform CPF transfer from OA to SA,  to max out year 2022 FRS S$192,000 in SA account.


Updated on April 4th, 2022
============================
The record was broken last month (March 2022), the 3 bedroom unit, 1,173 sq ft, floor level 11 to 15, was sold at all-time-high S$998,000. 

Saturday, January 1, 2022

Happy New Year 2022

Yup, on the first day of the new year 2022, we topped up our CPF accounts. We topped up maximum of S$3,000 each in our CPF MA account to reach Basic Healthcare Sum (BHS) of S$66,000 for year 2022. That will give us a good tax saving for year 2023. 

We also topped up S$6,428.44 into our kid CPF SA account to make the SA sum to be S$40,000.00 It will yield an interest of S$2,000 by the end of this year. 5% interest. Sweet! 

S$29,767.04 total CPF interest received today... 

0.82M41 for now...
Little CPF warrior in the making ...

Next windows to top up in MA to enjoy tax relief will be in March & October 2022 (for me).
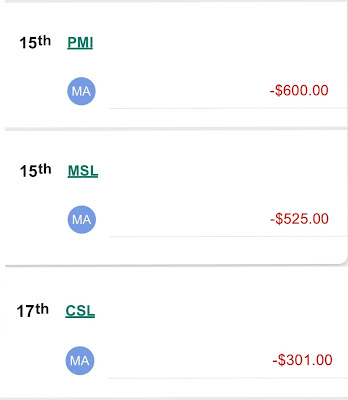
That's your H&S insurance and Careshield Life.

PMI : Private Medical Insurance
MSL: MediShield
CSL: Careshield Life


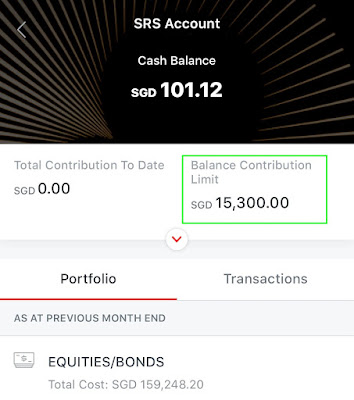
Next to top up maximum of S$15,300 each in our SRS account. The biggest tax saving is here. 

I have one good suggestion to do SRS S$15,300 top up if you want to preserve your cash for rainy days.

It is called "SRS Shielding". LOL. : )

It is defined as: sell your stock that was purchased in the cash account and re-purchase it immediately with SRS account.

The strategy is like CPF SA shielding just before the age of 55. 

You take out the CPF SA monies and park them elsewhere for few days then put them back to CPF SA account once the RA account is formed.

For example, if you have 1,000 DBS shares that you had purchased with cash in the past and the DBS stock price today is S$32. You can just use cash from your saving account (S$15,300) to top up into SRS account and you buy DBS shares at S$32. At the same time, you sell your DBS shares ( that you had purchased in cash) and the sale proceed goes back to your saving account. Done! 

So, literally you are transferring your DBS shares from cash account to SRS account and you enjoy good tax savings! Why not? You do this ONLY IF you don't have enough extra cash to top up into SRS account.

Of course, one will argue that it incurs the buying and selling charges but that amount is so small compared to the massive tax saving you are going to celebrate the following year. : )

I have re-invested close to S$160,000 into equities through SRS account.

I have yet to top up S$15,300 into the SRS account for the year 2022 but will do so soon.

Appendix: Latest CPF rules effective on January 1st, 2022.
HAPPY NEW YEAR 2022 !

Thursday, December 30, 2021

The CPF warriors

There are few CPF warriors on social media. We can learn from them.

The number 1 CPF warrior shall be ASSI ( AK71, born in 1971 probably).

He is so famous until many had used him as the benchmark. The graph below shows the graph of the OA balances. 

I don't know why the author only focused on OA balance but I would love to see the graph for the total balance of the entire CPF account instead.

AK71 CPF balance is astonishing. He received S$31,207.95 interest in year 2021.

That's S$1.08 million at the tender age of 50, 1.08M50 (alone). Very impressive.


Another folk born in year 1975. 

Good amount of monies in CPF OA, probably use cash only for housing loan?

It is quite weird that the MA account has not reached the basic healthcare sum (BHS) of S$63,000. 

SMK couple, 1.27M57
Mr. Loo has a pretty good homerun at his CPF OA by turning S$300,000 in OA to be S$423,000++ in just about a year plus. 

He basically dumped the CPF OA during the COVID era (April, May, June 2020) through Endowus platform by buying S&P 500. A very good catch indeed. 
1.27M48 achieved with combined S$470K+ in OA, S$590K+ in SA and S$127K+ in MA.
Two OA millionaires here, said to be age 56, and 57. (Retirement Account had been formed).

It is quite obvious that they both selected Enhanced Retirement Sum (ERS), that's why the RA account now is about S$300,000++. 

They did not do the SA shielding at the age of 55 as they both have low figures at SA account. 

If they have done the SA shielding, they will earn much more interest in the SA account instead of leaving S$1 million ++ in OA account.
Their CPF balances had further accelerated to S$1.762 million and S$1.619 million. 
Both of them are 2 years younger than PT, so PT is 59 then. :)
PT has a CPF balance of S$1.787 million.

The PT couple, probably the KING of the CPF Warriors, 3.26M59
He published a lot of information on social media which are good for our reference/benchmark. 
This ah boy reached FRS sum at SA at the age of 30. You can watch his video clip at Chris-HoneyMoneySG. Basically, you just follow the main first two procedures as early age as possible and you will be there (reaching FRS sum at SA) at the soonest.
(1) CPF SA & MA top up every year (to the maximum limit for tax relief).
(2) CPF OA to SA transfer.
(3) Do not use CPF OA to pay housing loan (if you own one).
One more CPF millionaire spotted. 
PB, 1.3M59 ( alone ) or 2.9M59. 

1M47 (alone) spotted. 
This is the best achievement seen so far. 
March 11th, 2022 will be her 48th birthday. CC.

Who will be the next CPF warrior? 

I would love to kick start my son CPF balance at the higher ground, currently S$44,515 @ age 9.

It is a good racing game, a rat race. LOL.


P/S: We are on track to achieve 4M65. 
Currently at 0.85M42 (as of July, 2022).
Or 1.13M42 (CPF Regrossed Balances, including the OA monies paid to the HDB private housing loan, Endowus/stocks purchase).

Saturday, December 18, 2021

CPF year 2022

December 2021 CPF balances.


Total net amount used in housing & accrued interest.

Magic 4.3% interest calculation for SA and MA, OA remains as 2.5%.

It came to the end of year 2021. as of December 18, 2021, our CPF balances stood at S$780,904.
On December 31st, 2021, I expect the CPF balances to be around S$810,366.
Total amount used in housing S$252,701.
CPF Regrossed Balances currently: S$1,056,964 (1.05M41).


As for my 9 years old boy, I still prefer the OLD CPF presentation as follow:
It is not difficult to predict the CPF interests as both SA and MA currently drawing the maximum 5% interest, which are S$1,600 interest in SA and S$215.02 in MA.

9 years old boy's CPF account balance: S$36,300.41.

Why I top up the child CPF in SA account instead of MA?
Technically, there are no differences as both account (SA and MA) yield up to 5% interest. 

He received the FREE S$3,000 from the government in MA account once he was born in September 2012. I would like to see the compound interest effect on the S$3,000 in CPF MA account by leaving the MA account untouched. 

That says all the MA account monies are FREE from the government. That's the reason.

The new CPF child account statement looks like this now:
Everyone must know your own expected/projected Full Retirement Sum (FRS) figure.
My FRS will be S$282,000.
My boys' FRS will be S$726,000.

Given FRS of S$250,000 gives S$2,000 per month from age 65 to life.
FRS of S$282,000 will give S$2,256 per month.
FRS of S$726,000 will give S$5,808 per month instead.

That's using the linear algebra extrapolation.
Understood that it is not perfectly linear, the estimated monthly sum is close/good enough for our knowledge and it is a good quick calculation. : )
National rally speech in year 2014.
You still can watch the full speech below:

Monday, October 11, 2021

What is your net worth ?


Many people nowadays are mesmerized by their net worth. 

Net worth is the value of all assets, minus the total of all liabilities.

In other words, net worth is what is owned minus what is owed. Simple.

Basically, the typical liabilities of Singaporean are either mortgage loan or car loan or both. That’s all about it or at least these are the two big ticket items.

Hence, I also keen to join the hype and calculate our net worth too!

What’s our liabilities? Mortgage loan and car loan la! See, it’s very common. I just told you! :)

Above properties AssetsValue = Market Value - Loan Liabilities

As of today (October 11, 2021), we still have a private home mortgage loan (liabilities) of S$856,612, car loan (liabilities) of S$64,033. In total, net liabilities of S$920,645. Nice. :(

You can obtain your monthly properties market value update from SRX. It is a very good information. We have cleared the HDB mortgage loan. 

The 4-room HDB flat has a market value of S$484,000, hence, that’s one of our good asset that generates a monthly passive income of S$2,150 (since 5 years ago).

The 4-bedrooms private property has a market value of S$1,630,000.

As for the car, even it has a liability of S$64,033, it also has an "asset value" of at least S$14,487. That is my car scrap value if I have to continue to drive the same car for another 9 years until the entire 10 years COE is expired. That says I will get back this value of S$14,487 in October 2030. 

Not too bad la. It is a fun car to drive. 


Hence, just for the 3 biggest assets calculation, we stand to have a net worth of S$1.207 million.

Thereafter, we can calculate the rest :
(1) Oversea properties (Malaysia).
(2) CPF balances (S$755,571 as of August 2021).
(3) Surrender values of Whole Life Insurance, Investment-Linked Plan, Endowment Plan.
(4) Liquid assets such as, banks savings, stocks equities, Endowus, SRS, etc..
(5) ASM 2 Wawasan: $35,494 (surrender value in year 2021: RM106,483).

The net worth, for a couple, will reach S$4+millions.


Our CPF at the maximum ...

A Singaporean household of 3. 2 working adults, age 46 (1980s) and 1 young adult age 14. Voluntary Housing Refund (VHR) all monies back to C...