Translate

Wednesday, July 13, 2016

Travel Insurance: Tokio Marine (TM) Xplora Annual (Classic Family)

Let's talk about travel insurance. I never buy travel insurance until my son was born. Before I bought the travel insurance, I also do not have any baggage delay or travel delay during my personal holiday. Isn't that cool ? Typically, people tend to pay a small sum for travel insurance per trip per person. In view of frequent travel with the family within a year, I decided to buy a family travel insurance, covering worldwide.


I picked Tokio Marine (TM) Xplora Annual (Classic Family) Travel Insurance.


It is my 3rd time buying this same TM Xplora Annual (Classic Family). The latest one is dated from February 4, 2016 to February 3, 2017.


The usual price of such worldwide classic coverage for family per year is S$453.


I forgot how I got 15% discount. I paid S$385.05 by using credit card (to collect points of course).
It is actually a very good deal if you travel a lot in a year or you have a big family.


This is the emergency contact to keep.


The coverage of the classic plan is shown below.


And the comparison between the Premier and Classic coverage.


Do take note that some of the coverage amount are exactly the same for Premier and Classic, for example, the travel delay and baggage delay are cap at maximum S$1,000 for both Premier and Classic.


For this year, we have made two claims. The latest one was my wife Hokkaido trip, flying from Singapore to KL then KL to Hokkaido. The flight from Singapore to KL was delayed for 2 hours. Hence, once she reached KLIA 2, she had to rush towards the boarding gate and she managed to board the plane as the last passenger.

So obviously, the luggage in the SG-KL plane is not able to be transferred to the other plane on time. So, she was aware that the luggage will not reach the destination once she arrived at Hokkaido. She bought Uniqlo cloths at the airport in Japan and continued her journey.

At the end, the luggage reached the hotel 48 hours later. So, the baggage delay claimed was max at S$1,000, measuring S$200 per 6 hours block. Baggage delay is fine but not baggage loss! So, the S$1,000 claim can help to pay her entire SG to Hokkaido airfare as it was an AirAsia budget flight and plenty more to spend !


The other claim was Micah doctor visit at the specialist at KL, total claim S$337.10. That's the two claims so far in this year.

The claim process is easy. Just fill up the form online through the website below. Thereafter you submit all the relevant document in PDF format, such as the passport details, boarding pass and the baggage delay reports.


While I was on the flight (March, year 2013) from Singapore to Washington D.C., transit at Dubai, my Emirates flight was delayed for 24 hours. All hotel stay and meals were provided by Emirates and that delay also entitled for travel insurance claim, travel delay. It was bad luck enough that even my return flight from Washington D.C. to Singapore, transit at Dubai, the flight was once again delayed for 24 hours (I was actually well prepared for this as the boarding time at Washington was delayed for 1.5 hours). So with both trips delayed, I was able to claim travel insurance max. of S$1,000 not with my personal travel insurance but with my company travel insurance as it was a business trip. You only can claim one travel insurance at a time.

Based on my record, we claimed S$417 doctor visit fees at KL for Micah in year 2014.


http://happysgpregnancy.blogspot.sg/2014/12/year-2014-micah-medical-bill_22.html


We also claimed S$552 doctor visit fees at KL for Micah in year 2013.


http://happysgpregnancy.blogspot.sg/2014/01/year-2013-baby-micah-medical-bill.html


That said if you have kid travel with you, you better buy family travel insurance. It is important to ensure that all the family members are well covered during the oversea trips as the cost is only S$385 per year per family , worldwide coverage.




Monday, February 29, 2016

Year 2016 Tuition Fees at Local Universities in Singapore (NUS , NTU & SMU) Revision 03

Revision 03: updated on August 28, 2019
Revision 02: updated on January 14, 2019
 
I have the latest figures (Year 2016) of the tuition fees at all 3x local universities in Singapore. Please take note that all fees are quoted in year 2016 annual subsidized fees. It means while you work for the first 3 years, you are slowly paying back the "subsidizes" to the government.

Somehow, the NUS and NTU fees are calibrated very close to each other, if not, exactly the same.

An engineering degree at NUS/NTU will cost you: S$31,800.

A business degree at NUS: S$37,400 while SMU: S$44,800.

Medicine at NUS: S$101,600.

Take engineering course as an example, S$31,800 for 4 years school fees, it is considered very affordable at today market.


For my curiosity, I just checked my U.S. university latest school fees in Michigan for the engineering course.

Undergraduate US$12,993 flat rate for one semester (1 year 2 semester, Fall & Winter), so US$12,993 x 2 semester x 2 years = US $51,972 ( lower level) + US$14,400 x 2 semester x 2 years) = US $57,600 . Total of 4 years school fees: US $109,572 = S$158,879.  And you are paying only S$31,800 in NUS. It is 80% cheaper.


Of course, the reason of the big differences are: you are studying in Singapore as a Singaporean versus studying in the United States as a non-resident (foreigner), that is why the cost has the big difference. Also, not everyone can enter the local university in Singapore, your A-Level grade must be good.

There are also some ways to reduce the cost of oversea studying by studying the first two years locally before doing the program exchange in the US, but the most you can save is about 50% of the total tuition fees quoted above in USD. After all, the price difference is still quite significant. Not to forget to add in the cost of residence, living expense, health insurance , etc.

So long the school fees increment is kept at low pace, I believe the tuition fees in Singapore is still within the reach.

To complete a Graduate program require 33 credit hours of course works. Hence, a Master degree in engineering will cost US $1,123 x 33 = US $37,059 = S$53,735. In other words, my certifications now has a market value of US $146,631 = S$ 212,614. That's crazy, how many years I have to work in order to breakeven that school fees ! :(

Good luck , kids, same goes to the parents. :)
 
Updated on January 14, 2019
=======================
 
All tuition fees increment are kept at a very reasonable pace.
 
From year 2019 onwards:
 
An engineering degree at NUS/NTU will cost you: S$32,800.
Tuition fees increment of 3.1% throughout 3 years.
 
A business degree at NUS: S$38,400 while SMU: S$45,800.
Tuition fees increment of 2.7% throughout 3 years for NUS and 2.2% for SMU.
 
Medicine at NUS: S$113,600 while NTU: S$136,800.
Tuition fees increment of 11.8% throughout 3 years for NUS and 4.6% for NTU.


Updated on August 28, 2019
=======================
 
Tuition fees for Singaporeans ! Still affordable, I shall say.


Monday, December 14, 2015

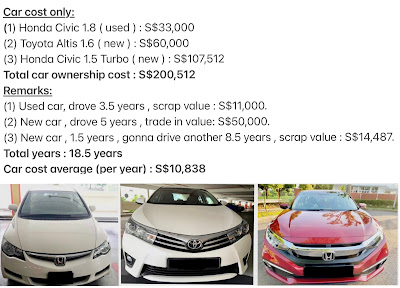
HONDA & TOYOTA (Revision 05)

HONDA CIVIC 1.5 TURBO: (Year 2020 - Present)
TOYOTA ALTIS 1.6: (Year 2015 - Year 2020)
HONDA CIVIC 1.8: (Year 2012 - Year 2015)

Just the car cost itself (with COE of course), the total car ownership cost for 18.5 years is S$200,512. 

In average, S$10,838 per year.


Revision 05 (last paragraph): updated on January 4, 2022.
Revision 04: updated on February 28, 2021.
Revision 03: updated on September 29, 2020.
Revision 02: updated on December 15, 2015.

I bought my first used car in April 2012. A pearl white Honda Civic 1.8 lit with a price tag of S$44,000. I have scrapped the car earlier in November 2015 with a return value of S$11,000. My COE will be expire in February 2016 instead.

So, literally, the car cost was S$33,000 for 3.5 years of usage (after getting back the car scrap value).

My beautiful used car:


April 2012 - car mileage was 84,206 KM
November 2015 - car mileage was 117,064 KM

In this 3.5 years of car usage, the car mileage clocked total of 32,858 KM.

In average, I run the car for 9,388 KM per year.


I finally know why everyone said Honda Civic is a reliable car.

For the past 3.5 years , I only spent S$2,344 for the car maintenance. It is average S$669+ per year! I only do car standard maintenance once in a year !

The Honda Civic car engine gave me zero problem for a nearly 10th year old car, can you believe it ? Zero problem !

Out from this S$2,344 car maintenance cost, it is good to point out the following items:

(1) I spent S$500 for 4 pieces of new car tyres.

(2) I changed my car battery in October 2012 and it still run well in November 2015 ! The car battery last for 3 years and more ! It is worth to mention the car battery is AMARON (12V 45 MAH type).

 
Of course, you have to pay insurance and road tax every year.
 
Road tax for 1.8 lit car is S$978 per year.
 
Car insurance average is S$1,600 and it will go lower and lower. I have yet to reach the 50% no claim limit discount.
 
Last but not least, you also need to include the car park fees and petrol cost.
 
In summary, I love Honda Civic car a lot. It is truly a fun car to drive.
 
I have since bought a brand new Toyota Altis in November 2015 and I will share more about the experience with Toyota here. Of course , Honda Civic is better than Altis but in terms of price, of course, Altis presents a much better value car, that is the key reason I bought Altis especially the new version of Altis looks so much better than the older generation, so, why not give it a try ?
 
So, this blog will be a continuous blog of my car experience with Toyota Altis thereafter. :)
 
Updated on December 15, 2015
=======================
 
Toyota Altis: (mine is pearl white again)


I bought a new Toyota Altis in early November 2015 with a price tag of S$110,000 nett.


It is a 1.6 lit. pearl white elegance series. It is a free upgrade that worth S$7,000.
 
This also include free 1 year servicing (4 times @ 1,000 KM, 5,000 KM, 10,000 KM and 20,000 KM). It has 5 years warranty for the car engine with unlimited mileage.
 
It is worth to take note the road tax for 12 months is now S$594 for a 1.6 lit. car.
 
The COE secured is S$56,001.
 
Do let me know if the Altis elegance series price start to drop below S$110,000 level. That has to be in line with the COE price drop, obviously.
 
My new baby now:


After driving almost 900 KM with Toyota Altis, let me share some views of this car in comparison with Honda Civic.
 
What I like:
 
(1) The price is great. At least it is cheaper than Honda Civic by S$15,000. I can use the price difference for Altis maintenance cost for 10 years ! :)
 
(2) The car looks great. The doors look like Lexus IS250. :)
 
(3) Even though it is a 1.6 lit car, the power is still not bad, acceptable.
 
(4) The noise isolation of this Altis is superb. It is extremely quiet once you close the door. I am impressed.
 
(5) Extremely fuel efficient. I will share more on that.
 
(6) And many more small little items like key less ignition, electric adjustable seat, built in GPS, auto LED light.
 
What I think it can be better:
 
(1) The steering wheel is too light for me but I somehow get used to it.
 
(2) The movement of the gear box is like a toy. Oh boy, luckily I don't have to change gear often like a manual car. The movement is not shiok like Honda Civic.
 
(3) The car compartment design is really bad. They should just copy Honda Civic. Civic compartment in the car is super.
 
Toyota Altis has a scrap value of S$9,800
Honda Civic scrap value is S$10,000
Honda City scrap value is S$4,500.
 
I have once calculated the standard and major maintenance until 80,000 KM ( I probably only able to clock 80,000 KM in 10 years time or lesser). The maintenance cost would be S$ 1,575 for 10 years from Toyota Service Centre. That's not too bad indeed. (The cost breakdown will be shared in the next revision).

Updated on September 29, 2020
=======================

I will trade in the Toyota Altis on October 13, 2020 for S$50,000 and I lost the car scrap value of S$9,800. 
Technically speaking , I paid S$60,000 to drive the new car for 5 years.
S$12,000 to own the car for a year. 
I have driven about 75,000 KM.

My next servicing is scheduled to be end of Q4 2020 and I skipped it due to the trade in.

Hence, my maintenance cost for this car was S$3,769.20. It includes new tyres cost of S$565.
In average, I pay S$753 per year. The cost does not include the road tax, VICOM car test, ERP, car park fees, etc..


As for the car insurance paid for the past 5 years, total paid: S$4,300++.


Goodbye Toyota Altis.

It is indeed a good reliable Japanese car. No problem at all. 


Updated on February 28, 2021
========================

(1) 13th October 2020
- New car collection!
- FREE 6 months road tax worth S$342.
- 5 years extended warranty (unlimited mileage)
- FREE 3 years servicing (7 times or up to 60,000KM)
- FREE front recording camera
- FREE Honda coilmat
- COE: S$41,510
- KahShield Undercoating/ Rustproofing, paid S$256.80.
- After 10 years scrap value will be S$14,487 (Minimum PARF Benefit)

(2) 30th October 2020
- paid S$540 for BlackNano coating (including windscreen coating on all glass panels, GYEON RIMS coating on all 4 rims, Interior coated with GYEON leather COAT and head and tail lamps coating. 36 months warranty, where covering gloss, uneveness of coating as well as peeling and cracking on the coating.

(3) 13th November 2020
- FREE first car servicing
- used Shell Helix Ultra 0W-20 Fully Synthetic Motor Oil

For the past 5 months car driving experience, I only can say this Honda Civic 1.5 Turbo indeed is a fun car to drive! 

Simply LOVE it !


Picked latest color in year 2020: Coffee Cherry Red Metallic.


Divine Exchange. :) Traded in 5 years old Toyota Altis for S$50,000.


Honda Civic 1.5 Turbo engine.


After NanoBlack coatings.


Used during the first FREE car servicing at Honda Service Centre.


Updated on January 4, 2022
========================
One year detail expenses for Honda Civic 1.5 Turbo are shown below.
Keep track the petrol usage for fun. : ) 
The Honda Civic 1.5 Turbo has a petrol tank size of 47 liters.
One year net car petrol cost S$2,136.77. 
That's S$178.06 per month.
Total distance traveled within a year: 12,378KM.
Total 1 year spent (1st year) : S$3,489.86 . Average per month: S$290.82.

I don't have to go through ERP gantry to work and also no ERP gantry when I drive back home.
I also do not have to pay for car park fee at work place as well as the residence place.

However, I do have to pay car park fee elsewhere and that can round out the average spent per month to be S$300.

Monday, November 30, 2015

Horizon Hills - Reap LOW Sell HIGH

I have the permission from the owner to share this piece of information. He is one of my buddies and also a successful investor.

He bought a Corner Terrace house at Horizon Hill, Gateway Precinct, unit size is 22” x 70” and land size is 32” x 70” during the launch time in year 2006 for RM 350,000. He spent about RM100, 000 on renovation, made it a beautiful sweet home for self-stay after the key collection in year 2009.
He then sold the unit in late year 2012 for a cool price tag of RM 1,250,000. That’s right, a windfall of RM900, 000 FAT GAIN.

This is a classic example of reaping at LOW price and sell at the PEAK. It is a pure luck. Sound like a stock market, isn't it ?
The new owner of the unit is trying to sell at RM1,000,000 and there are no takers yet. It is not a rocket science to know it is the timing of the market + beautiful renovation that fetch the previous PEAK price.

Oh ya, you also need some sheer luck to ensure that your neighbor unit don’t spoilt the potential buyers first impression. Some neighbors don’t really care about their compound and the grass just simply grows and it will deteriorate your house value if your unit is right next to it. You are daydreaming if you think your neighbor can be sold at “such price” meaning your unit can too. It depends, really, maybe even more?

That’s one piece of information to share. It is good news for all the Horizon Hill owners.

For all the potential buyers and sellers (regardless of what properties), you always need a bank valuation to obtain the housing loan. By then, you will truly know what is your unit market price. You can have all the sky high asking price but the buyer must be ready to fork out any differences between the asking price and the market valuation by CASH. It is the same for Singapore properties purchase too.

Good luck for all the investors.

Saturday, June 13, 2015

Summary: Investment Linked Plan/ Endowment Plan / Whole Life Insurance

After writing 3 articles about ILP, Endowment Plan and Whole Life Insurance in one day, it seems like many people are still confused about the three products. Hence, I shall draw summaries and key takeaways for these 3 products.

 Investment-Linked Plan (ILP)
------------------------------------------
 
Investment-Linked Plan performance is purely based on your selected funds. You can buy Singapore Growth fund, Asia Growth fund etc. You can also split your monthly payment, 50% into Emerging Country fund or 50% into China fund. So, your fund performance is solely depends on the funds you have picked. The projected 5%, 9% returns of course are non guaranteed portion. That is just an illustration if your fund yields a 5% return or 9% return. That is why there WILL NOT be any guarantee portion. How can an insurance company guarantees such guarantee returns regardless of the funds you have chosen? It does not make sense.
 
Endowment Plan
------------------------ 

As for Endowment Plan, there is no fund for you to choose from. You just buy and wait for the performance of the investment of the insurance company. Of course, they also take your monies and invest but you have no control, they have. Therefore, they do have guarantee portion for Endowment plan and as well as non guarantee portion. Usually, with endowment plan, the insurance company tends to be more conservative in investing because they need to make sure they are able to pay the guarantee portion. They will not bet your monies into high risk products or buying volatile stock like Genting share. Usually, people are buying Endowment plan for the purpose of discipline saving for certain purpose, for example, kid education fund, or even save money to have a certain lump sum pay out at certain age. This is the lowest insurance coverage plan, people will not buy Endowment plan for the insurance coverage as their objective.

 Whole Life Insurance
-------------------------------

As for whole life insurance, I do not understand why people are extremely sceptical about the performance of Tokio Marine by hitting the projected bonuses every single time. Well, maybe it just sounds too good to be true. There are some voices saying, if that is true, why they have this non-guarantee portion too. Well, we are in Singapore, every single product is regulated in the same manner/format. I would believe this is the regulation of MAS, I don’t know. This is the norm for every single insurance company to declare in such format, guarantee and non guarantee. Please don't ask me why, ask PAP. If you check carefully, Tokio Marine seems to give conservative non guarantee pay out compared to the rest of the insurance companies, simply because, I believe, they want to achieve that non guarantee pay out every single year as their trademark of the product. So they can’t just put a handsome number and then not hitting the mark at the end, just like many other insurances companies. Well, even for the marketing material advertised at the Straits Times, it has to be a true fact. If you doubt that, you can always check the figures yourself or even ask any insurance agents, they are all trained and they know all the truth and figures. Just ask a simple question, why the other insurance companies don't advertise in that manner? The answer is simple. They didn't meet the projected bonuses every single year. If they did, you think they don't want to advertise that too? Of course, other insurance companies will tell you the list of pros and cons for every single companies. Anyway, for whole life insurance, there is no funds for you to choose too. Insurance companies will take your monies and invest somewhere as well. They cannot place your monies in the bank and give you guarantee and non guarantee pay out, right? It is common sense that all insurance plans required certain type of investment to generate incomes.

Besides these 3 insurance products, there are other insurance plan namely, term insurance, hospitalization & Surgical insurance(H&S) and travel insurance. They are all the same “categories”.
 
Continue to pay money and no surrender value, zero value.
 
You just keep paying for the insurance coverage. That’s it. We all know many people prefer term insurance, because the premium is cheap or much cheaper than whole life insurance and the coverage is much bigger.
 
They will tell you the cost differences and the extra monies can be handled by themselves to do investment and generate better returns. That is one way of course. I do other investment myself too but I don’t like term insurance simply because I do NOT like the idea of ZERO value.

Our CPF at the maximum ...

A Singaporean household of 3. 2 working adults, age 46 (1980s) and 1 young adult age 14. Voluntary Housing Refund (VHR) all monies back to C...