Translate

Monday, October 11, 2021

What is your net worth ?


Many people nowadays are mesmerized by their net worth. 

Net worth is the value of all assets, minus the total of all liabilities.

In other words, net worth is what is owned minus what is owed. Simple.

Basically, the typical liabilities of Singaporean are either mortgage loan or car loan or both. That’s all about it or at least these are the two big ticket items.

Hence, I also keen to join the hype and calculate our net worth too!

What’s our liabilities? Mortgage loan and car loan la! See, it’s very common. I just told you! :)

Above properties AssetsValue = Market Value - Loan Liabilities

As of today (October 11, 2021), we still have a private home mortgage loan (liabilities) of S$856,612, car loan (liabilities) of S$64,033. In total, net liabilities of S$920,645. Nice. :(

You can obtain your monthly properties market value update from SRX. It is a very good information. We have cleared the HDB mortgage loan. 

The 4-room HDB flat has a market value of S$484,000, hence, that’s one of our good asset that generates a monthly passive income of S$2,150 (since 5 years ago).

The 4-bedrooms private property has a market value of S$1,630,000.

As for the car, even it has a liability of S$64,033, it also has an "asset value" of at least S$14,487. That is my car scrap value if I have to continue to drive the same car for another 9 years until the entire 10 years COE is expired. That says I will get back this value of S$14,487 in October 2030. 

Not too bad la. It is a fun car to drive. 


Hence, just for the 3 biggest assets calculation, we stand to have a net worth of S$1.207 million.

Thereafter, we can calculate the rest :
(1) Oversea properties (Malaysia).
(2) CPF balances (S$755,571 as of August 2021).
(3) Surrender values of Whole Life Insurance, Investment-Linked Plan, Endowment Plan.
(4) Liquid assets such as, banks savings, stocks equities, Endowus, SRS, etc..
(5) ASM 2 Wawasan: $35,494 (surrender value in year 2021: RM106,483).

The net worth, for a couple, will reach S$4+millions.


Wednesday, August 11, 2021

Toh Guan Grove (Aug 2021 Build-To-Order)

I bought my 4-room resale flat, 90 sqm (high floor unit) at Toh Guan in June 2009 at S$355,000.

Market Valuation: S$360,000.

S$5,000 below valuation because the owner knocked down the wall of one bedroom (bedroom 3 shown below) to merge with the living hall. I re-built the bedroom wall at less than S$1,000. :)

Keeping the information below for future references.

HDB | BTO Project Details

For the first time in 10 years, the non-mature estate of Jurong East will get its first new flats. A total of 569 two-room flexi, three-room and four-room flats are on offer at Toh Guan Grove, which sits near the upcoming Toh Guan MRT station on the Jurong Region Line.

Prices start from $237,000 for a three-room flat and $347,000 for a four-room flat.
The estimated completion date is in the first quarter of 2026, so buyers have to wait about four years for their homes.
The last BTO launch for Jurong East was Teban View in September 2011, where some 518 three- and four-room flats were released for sale.
Prices then started from $158,000 for a three-room flat and $271,000 for a four-room flat.
If I am given a choice to purchase a unit here, I will purchase the highest, the biggest unit, S$436,000. You set to gain the maximum profits if you intend to sell next time after the MOP.

Based on the site plan below, there are 7 choices, namely, stack 291, 293, 295, 301, 307, 309 and 311.

I will pick stack 295.

Stack 301, 309, 311 are west-sun facing.
Same for the stack 291 and 293 but not too extreme.
That leaves with choice of stack 295 or 307.

Stack 307 facing is not bad but there is a bus-stop at the opposite street. The bus noises can transmit to the high floors easily.

Stack 295 is almost perfect but do take note there is a pavilion next to it. You know all kind of events can be held there but again at the highest floor, you shall not be affected by the activities below.

Hence, my choice will be stack 295.


Saturday, July 31, 2021

Typical ways to enjoy tax relief / tax savings in Singapore & GROW your CPF balance exponentially !

There are few typical ways to enjoy tax relief in Singapore and at the same time, build up a strong retirement income. Kill 2 birds with 1 stone. Nice! 

There is a cap now for the tax relief, which is S$80,000. It is sad for the working mothers as they can easily burst the S$80,000 ceiling if they have children.

(A) Enjoy tax relief / tax savings :

(1) Hitting CPF Annual Limit (AL) of S$37,740 to enjoy maximum tax relief of S$20,400, be it your high salaries/bonuses or you do Voluntary Contribution (VC) to your CPF MA account (to hit the Annual Limit) if your MA is below Basic Healthcare Sum (BHS).

(2) CPF Cash top-up to SA account to enjoy S$7,000 maximum tax relief. Enjoy while it lasts. It can be done until SA reaches Full Retirement Sum (FRS).

(3) SRS contribution to enjoy S$15,300 maximum tax relief. Then buy S&P500 fund (through Endowus), local equities / REITs, etc. to grow your monies in SRS account further!


Of course there are other tax relief you can claim if you are eligible, for example: 
- NSman-self/wife/parent, 
- Course Fee, 
- Cash top-up to parent CPF, 
- Parent relief, 
- Foreign domestic worker levy
- Earned income relief
- Qualifying child relief 
- Working mother child relief (this is one massive tax relief for female working mothers)

(B) No tax relief/ tax savings:

(1) Transfer CPF OA to SA to enjoy additional 1.5% interest. This cannot be done once SA reaches FRS.

(2) VHR (Voluntary Housing Refund) back to your CPF OA.

(3) Top up kid's CPF SA to enjoy 5% interest (for the first S$60,000, thereafter 4% interest).

(4) CPF SA shielding only when you approach age 55, that's just one time in & out. Some will even want to shield OA account. There are many articles out there to teach how you to do CPF SA shielding. Go check it out!

By doing all above diligently, there is no way you cannot see your CPF balance goes up exponentially. You build up a strong retirement income and yet enjoy a good tax savings. 

Good luck and enjoy hacking the eggs!

Friday, July 2, 2021

CPF Annual Report 2020 (1M41 Regrossed Balances)

CPF annual report 2020 just released !

Benchmark our CPF balances with the national data with the "All CPF Members" table.


With regrossed balance definition, we have a combined S$1.029 million dollars in CPF. : ) That sounds better. 

Anyway, pure cash balance in CPF account would be S$754,901 instead.

The key is to stay employed. 

The regrossed balance includes the monies you have spent on investment / housing loan / education, etc. . I personally think that is the right way of calculating as that shows your ability to draw cash into the CPF account (be it yourself or from the employer contribution). Nevertheless, it excludes how well your stocks/ Endowus performance in the CPF OA account too as they only count the amount you throw in. That says, if your stocks/ Endowus perform well above 2.5% given by the CPF OA, you will expect much larger sum at the moment you sell and return back to CPF OA! Vice versa.

We have achieved 1M41 and now targeted 4M65. 
See blog below.
JK Holdings: CPF Regrossed Balances benchmark & CPF Balance Projection (Achieved 1M41 & Target 4M65) (jkfund.blogspot.com)

Here are the subsequent years of CPF data for references from year 2014 to 2020.

Some interesting points:

(1) They only published ALL CPF members data in year 2019 and 2020. In fact, they published ACTIVE CPF members data from year 2014 to year 2020.

(2) They used to publish the highest category of S$150K & above only from year 2014 to year 2018 but from year 2019, they now also publish additional 10 higher tier categories with the highest category of S$500K & above. Maybe they shall publish all the way to S$1million & above category in the future too.

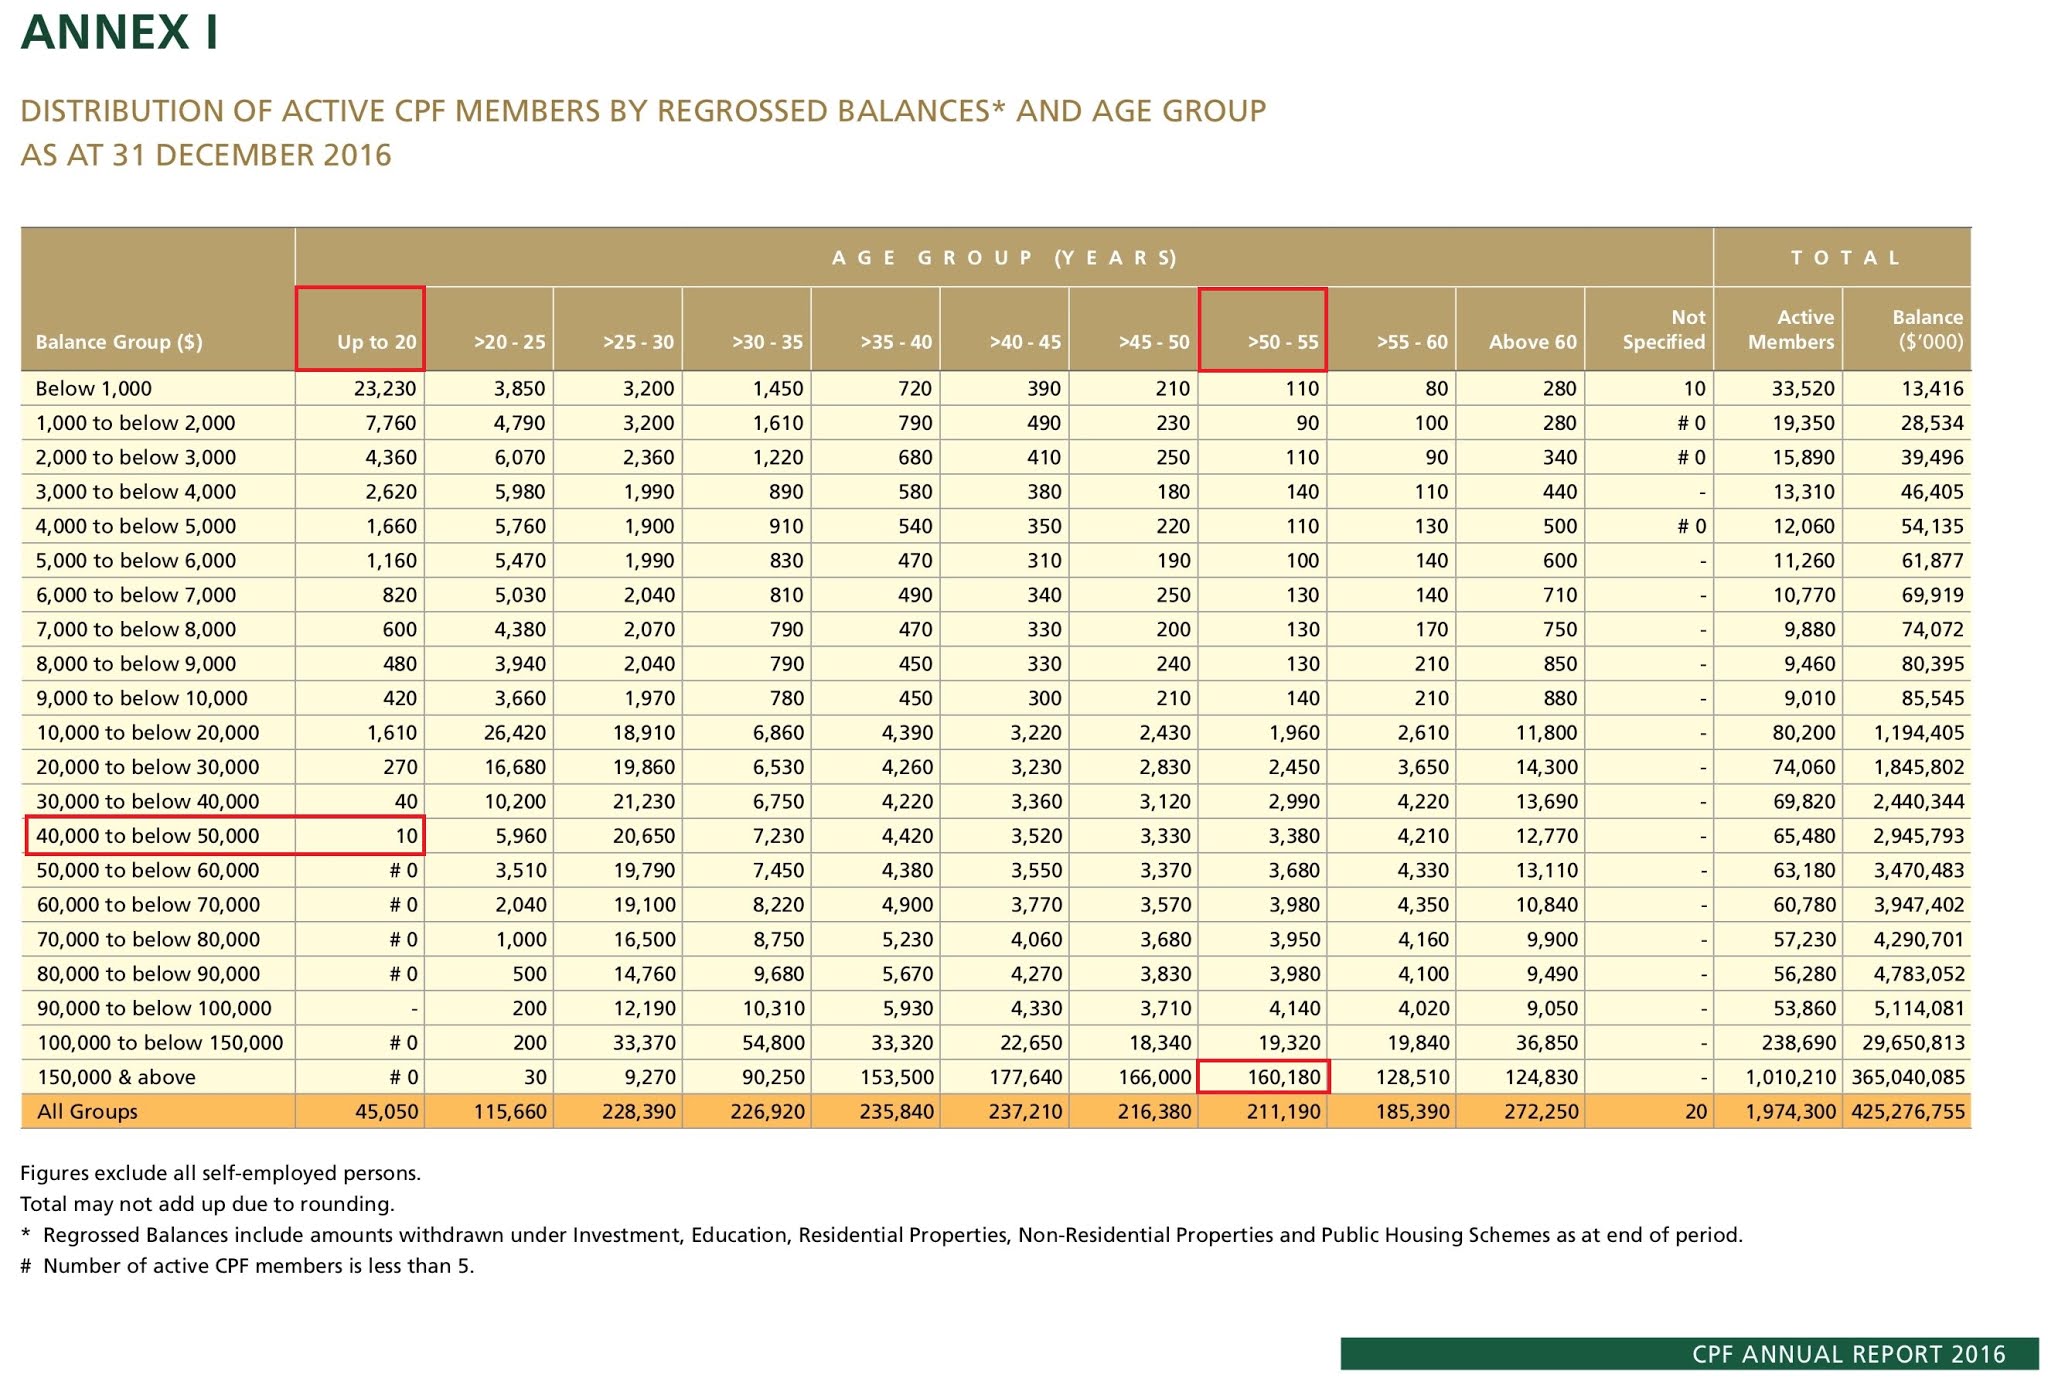
(3) From the ACTIVE CPF members data from year 2014 to year 2020, you can see there is a steadily increase of members in the S$150K and above category at age group of 50-55. The percentage shoot up from 71.5% to 84% (corresponding to the total active members at age group of 50-55. It is a healthy increment. That actually says 84% of the active CPF members at age 50-55 group is able to meet the Full Retirement Sum (FRS). Good trend. Provided that they do not use too much OA monies on housing loan.

(4) As for ALL CPF members data from year 2019 to year 2020, let's look at the youngest category of "up to age 20", the top categories S$300K to 400K remains the same as 10 members. There is an additional 100 members at S$80K to S$300K range and an additional 50 members at S$60K to S$80K range, etc. Interesting, more and more parents are topping up their kids' CPF account obviously.

(5) 840 members having S$40K and more in the "up to age 20" group. This number will continue to rise. It has increased 38% from 610 members in year 2019. My son will join this “S$40K and more” category next year too. :)


ALL CPF members (Year 2020)
ACTIVE CPF members (Year 2020)
ALL CPF members (Year 2019)
ACTIVE CPF members (Year 2019)
ACTIVE CPF members (Year 2018)
ACTIVE CPF members (Year 2017)
ACTIVE CPF members (Year 2016)
ACTIVE CPF members (Year 2015)
ACTIVE CPF members (Year 2014)

Updated on August 26, 2021
====================
The goal is to have S$400,000 each at the start of the new year 2022 !

Friday, June 4, 2021

Whole Life Insurance, love it !

In year 2021, we spent a good sum of S$23,048.36 for insurance for a household of three.

I want to talk about the beauty of whole life insurance here.

I have fully paid up the whole life insurance for my son as I shorten the payment term to 5 years only. It is a done deal. :)

As for our own whole life insurance plan of 20 years payment, we will fully settle the whole life insurance plans in 5 years time. 

What is the strategy of our whole life insurance plan? It is simple, only 2 options.

Option 1:
We should never surrender the whole life insurance plan. That's insurance, dude!
It is meant to pass on the death benefits sum to your loved one once you are dead. 

Option 2:
If you have no loved one or you want to surrender the plan for future retirement income, you can do so but make sure you surrender the whole life insurance plan as late as possible. How late?

At the age of 55, you can start to withdraw CPF monies as much as you want after setting aside Full Retirement Sum (FRS) to RA (Retirement Account). Hence, you definitely DO NOT WANT to surrender at such age.

From the age of 65, you start to receive CPF LIFE monthly payout until death. 
S$2,000 a month for each of us (FRS sum will be S$250,000 at our age of 55).

From the age 62 to 71, you also start to withdraw monies from your SRS account, spanning 10 years horizon. 

Hence, in my opinion, the best time to surrender the whole life insurance plan is at the age of 72 and above if you really do not want to pass on the death benefits to your loved one. That's fine. 

What's the surrender value ?

My son, at the age of 71, he will receive cash payout of S$444,843.

At my age of 71, I will receive cash payout of S$195,580.

At my wife age of 72, she will receive cash payout of S$150,027.

Me and my wife total payout of S$345,607 is a tidy sum at the age of 71/72. 
Not one cent more, not one cent less. That's Tokio Marine. 

In addition, there is also one Whole Life Insurance from Prudential with a surrender value of S$130,206 at her age of 73. That brings to the total of S$475,813 payout from Whole Life Insurance. 

Why so many people still dislike Whole Life Insurance?

Just because of the phrase "buy term & invest the rest" will eliminate all the goodness above?
I don't think so.

I can always still buy term insurance anytime to boost up the coverage if I want to. 
Invest the rest? I have already done so.

That's my strategy of Whole Life Insurance, love it!


Our CPF at the maximum ...

A Singaporean household of 3. 2 working adults, age 46 (1980s) and 1 young adult age 14. Voluntary Housing Refund (VHR) all monies back to C...