Translate

Monday, October 13, 2014

Is it really worth to go into Johor just for the car petrol? (Revision 03)

Revision 03 (last paragraph): updated on March 1, 2016
Revision 02: updated on October 14, 2014

Do you hear your friends or colleagues always go into Johor for the cheaper car petrol ? How much they really save? I know some crazy folks just enter Johor, pump the car petrol to full tank (maybe shaking the car boot) and U-turn back to Singapore, is it really worth it?

FORGET IT.

Don't waste your valuable time and energy.

Singapore cars can only pump Fuel 97 in Malaysia. The current price now is RM 2.75. It will become RM 2.915 if government imposes 6% GST on Fuel 97. Let's see.


There are still many people do not know this biggest promotion in Singapore. The promotion had been in the market for years ever since I got my car in Singapore.

The total discount is always 20.1%.
Only recently, with the new SPC & U card, your total discount now is 21.98%.

NO ONE is paying the usual fuel price in Singapore.


 There are some key remarks you should take note:

(1) Let's assume you can pump 40 lit. full tank.
(2) Before entering Malaysia from Singapore, the rule requires you to have at least 3/4 tank of fuel. Meaning to say you only have 10 lit. free space.
(3) Okay, plus minus, you make a day trip to Johor, say you spend another 5 lit. That's a total 15 lit. of free space, how much do you really save? Do you ever calculate ? 35% is the exact percentage right now, BUT...

For 15 lit. car petrol, you only save S$8.90. Does it worth it? How much is the toll charges in Singapore custom ? How much is the toll charges in Malaysia custom ? How much wasted fuel for the distance you have traveled from Singapore to Johor and from Johor back to Singapore just to pump the car petrol ?

Do you calculate the jam in the traffic? Your time? You think you really save S$8.90 after deduting all the above?

Maybe S$0.90 for all the hassles.

Of course, now you will hear another set of voices saying, we go into Johor for bunlde activities. We makan lunch, makan dinner, foot massage, cinema movie, etc.

Well, that does not really help you to save more, maybe you increase your expenses just because you think such services are cheap and you want to go ALL for it and actually you don't even need it. :)


P/S: I know the calculation above is "unfair" between the Singapore Fuel 95 and Malaysia Fuel 97. Well, that's what majority of the Singaporean do.

Updated on October 14, 2014
=====================
One blog reader is quick to point out that 15 lit. of car petrol can't even save you S$0.90 if you include the total toll charges! He is absolutely right !

Causeway total toll charges now for round trips with car is S$12.80.
Tuas second link total toll charges for round trips with car is S$12.40.

15 lit. car petrol only save S$8.90 !

The breakeven cost is 21 lit. car petrol which manage to save S$12.45 and it will be fully wiped off by the toll charges for round trips!

If 6% GST is imposed to fuel 97, the breakeven cost is 24 lit. car petrol which saves S$12.65 only.

And yet that does not include the extra journey travelled just to pump the car petrol and the crazy traffic jam at the custom!


Updated on March 1, 2016
===================

Singapore government is reviewing to remove the "3/4 tank filled rule". Are they serious? Johor-Singapore customs will be jam packed even during the non-peak hours if such rule is removed. I doubt they will remove it.


The price of Ron 97 is now RM 1.95. Such price was seen in year 2008. I have the information of the car petrol price exactly on March 2 , 2015 versus March 1, 2016. Let's see what are the differences.

The toll charges remains the same as SGD 12.40.

So, instead of breakeven the toll charges at 17 lit. of car petrol pumped, it is now 16 lit.

Even if Singapore government removes the "3/4 rule", the most you can save is S$19.77 per trip. Not to mention the "additional distance" you travel all the way there and your valuable time.

Is it still worth it ? Well, if you bundle up ALL the activities, why not?

It is simple for me, entering Johor is FREE and with some gain (S$7 ++ gain still after minus the Tuas toll charges) simply because I always pump around 25 lit. of petrol. Will I go there just for the petrol only? No.

Receipt was dated February 2016


Thursday, October 9, 2014

CIMB HomeFlexi (Malaysia Housing Loan)

I get to know this CIMB HomeFlexi housing loan recently.

This is the general features of HomeFlexi published at CIMB website.

Just a few notes:
(1) There is a monthly service charge of RM 10 only. You can easily earn this back with the interest you have saved.

(2) You can park your money at the current account (just like saving account, NOT housing loan account) and save the interest. You can withdraw the money anytime without any service fees. Of course, your loan interest amount will be added back.

(3) Exactly how much do you save as compare to put the money in the fix deposit? Actually, it is just a mere saving of 1+%. I have one example below.


There are three scenarios here:
(1) You place RM 50,000 into the current account
(2) You place RM 100,000 into the current account
(2) You place RM 150,000 into the current account

Assuming, your property is completed and the full monthly installment kicks in.

When you make the monthly instalment of RM 3,461.25, RM 2,730.08 will go into the interest portion (that's the first month).

Hence, if you have placed RM 50,000 into the current account, the interest for that month actually reduced to RM 2,544.66. You are still paying RM 3,461.25, but your monthly principal actually increased (because you reduce the interest) , so you are actually paying RM 916.59 for monthly principal instead of RM 731.28 (this figure is for the first month as an example).

Same goes for RM 100,000, your monthly interest reduced from RM 2,730.08 to RM 2,359.24.

As for RM 150,000, your monthly interest reduced from RM 2,730.08 to RM 2173.83.


Assume you place this RM 50,000 , RM100,000 and RM150,000 respectively into Malaysia fix deposit for 24 months and the interest rate say 3.3%, you will find out, you rather put the money back to the current account.

You can actually save additional 1.1% P.A. Hence, you can actually get 4.4% interest instead of 3.3% from the fix deposit. The saving is nothing fantastic but you have the good saving with great flexibility.

As for the new launch residential purchase, your first 3 years is progressive payment. Hence, if you put an amount of RM 150,000 , your first year housing loan might be 0% interest. That is pretty cool eh ?


Thursday, September 25, 2014

Happy SINGTEL customer since day 1 (Revision 04)

 
Revision 04 (last paragraph): updated on April 3, 2021
Revision 03: updated on March 7, 2015
Revision 02: updated on October 6, 2014

This blog is EXCLUSIVELY for Singtel MIO Plan customer. If you are Singtel mio Plan customer, you should pay attention to this blog.

I received the letter from Singtel informing me that mio Plan will no longer be available for re-contract. I had signed up this great Singtel plan since year 2006.

For mio Plan, I pay S$76.47 nett monthly for my home broadband, home phone and mobile phone.

I have two options (Fibre options below are not available for public, only for mio Plan customers):

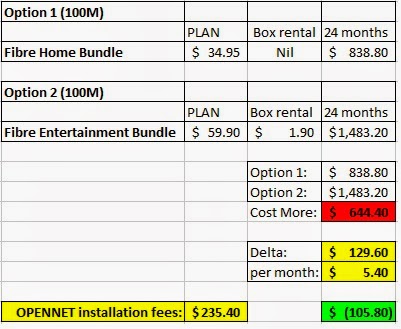
Option1: COMBO 2 mobile plan + Fibre Home Bundle (100M)

Mio Plan customers are given special price on Fible Home Bundle which is only S$34.95 per month. COMBO 2 mobile plan is the same as public, which is S$42.90 per month.


Option 2: COMBO2 mobile plan + Fibre Entertainment Bundle (100M)

Mio Plan customers again are given special price on Fibre Entertainment Bundle which is only S$59.90 per month. COMBO 2 mobile plan is the same as public, which is $42.90 per month.


It is not difficult for me to decide which option to go, clearly option 2 is the most valuable one and why?

(1) Option 2 can enjoy yearly handset upgrade just like mio Plan but Option 1 can’t.

(2) Option 2 can enjoy mobile multi-line discount of up to 30% for five Singtel Mobile lines but Option 1 can only enjoy 10% discount for 1 line only.

(3) Option 2 can enjoy free waiver of S$235.40 OPENNET installation but Option 1 can’t. It is my bad rejected OPENNET installation last time but now it is a must to have this OPENNET installation. Please take note!

(4) Either Option 1 or Option 2, both plan Singtel is giving me additional S$200 hand phone discount.

A big WOW, I just re-contract my line in March 2014 with a Samsung Galaxy tab for only S$30 and I sold it at hardwarezone.com for a cool S$280. And now shortly after 7 months, Singtel allows me to do the re-contact yet again! Usually mio Plan customer can re-contract after 12 months. Not only Singtel allows me to do the re-contract after 7 months, they even give me a S$200 hand phone discount! This offer is valid until October 31, 2014. Simply too good to be true.

So, with COMBO 2 plan, iphone 6 costs SGD 508, free SGD 200 discount from Singtel, trade in price of iphone 5 (from Singtel) is SGD 200, I only need to pay SGD 108 for a brand new iphone 6. BUT GUESS WHAT? I managed to trade in my iphone 5 (16GB) for SGD 320 on September 26 at EZY Mobile shop at Holland Village. They paid SGD 120 more than Singtel ! In short, I traded in my iphone 5 with iphone 6 for FREE and yet I gain S$12. Ha ha. That's really cool !

Or stick to your iphone 5, and sell your iphone 6 for S$1,000 or more at hardwarezone again, why not? Then, your 2 years phone bill is completely FREE. :)

How much we are really paying if we opt for Option 1 or Option 2.

If I choose Option 1, my mobile phone can enjoy 10% but my wife mobile line will have 0% discount.

So, two of us, 2 years cost us S$2,213.04

If I choose Option 2, (I had gathered 3 more Singtel mobile line to enjoy 30% ) my mobile and my wife mobile both can enjoy 30% discount. You MUST take this benefits.

So, two of us, 2 years cost us S$1,698.24, that’s instant saving of S$514.80. That is mobile plan.


As for Fibre plan:

If I choose Option 1, Fibre Home Bundle, it is easy, I need to pay S$34.95, 2 years S$838.80.

If I choose Option 2, Fibre Entertainment Bundle, I need to pay S$61.80 per month (take note on the rental box of S$1.90 charges per month), 2 years S$1,483.20.

So, the difference is ONLY S$129.60 EXTRA for the entire 24 months contract by calculating the cost saving of mobile plan, S$514.80. That is ONLY S$5.40 EXTRA PER MONTH for you to watch 55 oversea TV channels, include Bloomberg, National Geographic Channels, Disney channels for your kids, etc.

But WAIT, for me, if I choose option 1, I have to pay OPENNET installation fees of S$235.40. That is just me. I know many of you get this done for free but if you have not done so, please make sure you have this installed else you will face problem in the future.

So, with that installtion fees come into calculation, I actually got completely FREE 55+ TV CHANNELS and yet I SAVE S$105.80 if I choose option 2. Furthermore, I can have new handset upgrade every year and I make 3 more friends happy to enjoy 30% discount on their mobile line.

What a great plan from Singtel.

Now, who can tell me what is the good bargain for a nice Ultra High Definition (UHD) LED TV at the current market? :)

Oh ya, by the way, please make sure you pay all the Singtel bills using OCBC 360 credit card, you got the entire bill a further 3% discount. Effectively, your mobile plan is 33% discount per month, like it?


IN SUMMARY (my case):

(1) IF and ONLY IF mio Plan still exist (not possible):
      MIO PLAN + 1 MOBILE LINE (30% discount)
      24 months - S$2,684.40

(2) If I choose only Fibre Home Plan:
      Fibre Home Plan (10% for MOBILE LINE) + 1 MOBILE LINE (No discount given)
      24 months = S$3,287.24

(3) If I choose Fibre Entertainment Plan:
      Fibre Entertainment Plan (30% for MOBILE LINE) + 1 MOBILE LINE (30%)
      24 months = S$3,181.44

Decision made: I have signed up for Fibre Entertainment Plan. Next hunting for a new UHD LED TV. :)

Updated on October 6, 2014
====================
I had purchased a LG 49UB850T model, Ultra High Definition , 49 inch, 4K Cinema 3D Smart TV from Courts at JEM mall on September 28, 2014. The TV delivery and installation was on October 4 and I found out the price difference of S$110 at Best store at IMM mall on October 5 , hence Courts has a policy for their buyer to get a refund of double the price difference, so I got S$220 ! :) There are also many promotion going on right now.

I total paid S$2,198 on the bill. With all the LG promotion, Courts in-house promotion, refund of double the price difference, Standard Chartered Manhattan credit card 3% cash back, etc.

I total received S$520 vouchers (combination of NTUC and Courts vouchers) and cash back of S$96.

Hence, you can say I total pay S$1,582. :)

My TV selection is rather simple. I want a Smart TV, 50 inch preferably. This TV has a refresh rate of 1,000 Hz ! Resolution of 3840 x 2160. The 3D feature just come with it. :)

The TV packaging.


 Courts refund of double the price difference policy.


 My TV at home!


Mio TV installation only took 40 minutes and I am given two wireless network channels to choose from. One is 5G wireless network. :)

Based on the speedtest.net test results, my home 5G wireless network yields download speed of 92 Mbps and upload speed of 114 Mbps. That's close to my 100 Mbps broadband subscription.

 I chose the most basic mio TV channels which has the following 55 channels. :)


Updated on March 7, 2015
====================
 
This is a typical normal bill of the cheapest SINGTEL MIO TV plan package you can get in Singapore. If you are STARHUB customer, please share your bill too as I am curious to know as well.
 
MIO TV program + 200 Mbps wireless broadband + MIO Home Voice = S$ 61.80 (including GST)
Cell phone package = S$35.38 (including GST, caller ID and 30% bundle discount)
Payment made by OCBC 365 Credit Card, you enjoy further 3% cash rebate.
 
In short, I paid S$94.26 on SINGTEL bill every month!
 
I am a long time happy customer of SINGTEL since year 2004. I should buy their stock too!
 
Furthermore, SINGTEL recently upgraded my broadband speed from 100 Mbps to 200 Mbps FREE. How crazy is that? Simply love it !


Updated on April 3, 2021
======================

It is time to update my SingTel plan after 6 years! I am still a happy SingTel customer since year 2004.

I just re-contracted my SingTel Mobile in March 2021, SingTel Fibre Broadband and SingTtel TV in April 2021. Net monthly payment is S$106.93. :)

(1)  I decided to keep using my iPhone 11 Max Pro. Hence, I re-contracted SingTel Mobile plan to get a new iPhone 12 Max Pro and re-sold it at the gain of S$322.
It is still a SingTel Combo 2 plan with Caller ID and DATA x 3 features. More than enough for me.
(2) I re-contracted the SingTel Fibre Broadband (1Gbps) with FREE 4 months fees, a saving of S$199.50.
(3) I also re-contracted the SingTel TV (Family Starter) with FREE 3 months fees, a saving of S$89.70. 
Total savings of S$611.30 to re-contract all 3 SingTel plans for another 24 months. 
My next re-contract eligibility will be in September 2022 (for SingTel mobile plan, just in time for Apple iPhone 14 launch) and  January 2023 (for SingTel Fibre Broadband and SingTel TV plans).
One task done. :)
I re-contracted and received the iPhone 12 Pro Max 128 GB (Pacific Blue) on March 1st, 2021.
I do not enjoy the S$50 off handset with 5G as I continued with my 4G plan instead, hence I paid S$1,238 for the phone.


The trade in price for the new iPhone 12 Pro Max 128 GB on March 1st, 2021 was S$1,600.


However, all the new phone from SingTel will be activated, hence they deducted S$40.
Net trade in price was S$1,560 instead.

Tuesday, September 2, 2014

Retirement Planning in Singapore: SRS Account (Revision 04)

Revision 04 (last paragraph): updated on March 4, 2015
Revision 03: updated on October 14, 2014
Revision 02: updated on September 6, 2014

Retirement in Singapore is always a hot topic. Many people are questioning if CPF is indeed enough to retire in Singapore. Nobody can tell you how much you need to retire but I am going to show you what you could/ should do now in order to have good retirement life in Singapore.

SRS (Supplementary Retirement Scheme) Account.

Many people misunderstood SRS account to CPF account. It is totally two different independant accounts. I only opened SRS account last year together with my wife. This is an alternative option for us to save for retirement.

There are couple of key points you should know about SRS account:

(1) The maximum contribution per year is only S$12,750 for SC and SPR, S$29,750 for foreingers.
(2) Your contribution will reduce your taxable income by S$12,750 max per year for SC and SPR.(The tax savings is great and that's our primary objectives)
(3) Upon retirement, only 50% of the amount withdrawn will be taxable. (You can and you should spread the withdrawals over 10 years upon retirement, you hardly need to pay a single cent based on the income tax structure today.)
(4) Earn interest of 0.05% p.a. on your cash balances in your SRS account. (This is definitely not the reason you contribute to SRS, for 0.05% interest? Hence, use the money in the SRS account to buy good stocks, ETF, index funds, fix deposits, unit trusts, life insurance, etc.)
(5) You can withdraw the money at any time. However, a 5% penalty for premature withdrawal applies, should the withdrawal be made before the statutory retirement age. (You should keep the money inside, that's for retirement purpose!)

Example 1:

This is to show you the SRS returns based on (6%, 7% & 8%).

Always remember:
Real Gain = (1) Tax Savings + (2) Dividends received + (3) SOLD stocks transactions

I would say 6% is very easy to achieve as you have confirmed good tax savings in the calculation and with good solid blue chips dividends, you can easily hit 4-5% or REITS easily 6-7% dividend yield. Not to mention, you have 30 years horizon to witness the price appreciation of the good quality stocks.

With conservative 6% calculation, your portfolio should yield S$1.288 million by the age of 62. Why age 62? It is because you SHOULD start to withdraw money at the age of 62, spreading 10 years, you have at least S$128,800 per year from age 62 to age 72. This is a great retirement side income, don't you think so?


Example 2:

This is how I keep track my SRS portfolio in yearly basis. I just contributed last year December. So, I only monitor the savings which kicks in this year. So far, I have hit 10.43% in the first year (due to some SOLD stocks transactions).

I set a rather high target myself. I would like to achieve 10% gain every year. With the help of tax saving amount, I would say it is NOT IMPOSSIBLE to achieve, let's see down to the years.

With 10% p.a. returns (stretch goal), the portfolio can yield S$2.307 million by the age of 62. The power of compound interest kicks in!


With CPF account and SRS account, two pillars, rest be assured you can retire comfortably in Singapore.

Updated on September 6, 2014
======================
A correction of the SRS returns per year, 10% is too low. It has to be much  more.

Real Gain = (1) Tax Savings + (2) Dividends received + (3) SOLD stocks transactions

Based on the above calculation, the (1) Tax Savings per year is already >S$1,275.

With yearly maximum contribution of S$12,750, the tax savings itself is already well pass 10%.

With (2) and (3) added into calculation, the percentage has to be more. Of course, your capital will keep increasing each year, your tax saving per year >S$1,275 is " >10% of your contribution of S$12,750 ONLY", you have to work harder with your remaining balance when years go by.

With that calculation, my first year return shall now be 20.9% instead. :)

Or to make the calculation "fair", your tax savings shown in the IRAS statement in year 2015 should be added into the year 2014 Real Gain formula because that is the saving results due to your SRS contribution in year 2014. :)

Updated on October 14, 2014
======================
Under the Retirement and Re-employment Act (RRA), the statutory minimum retirement age is still 62, but employers are now required to offer re-employment to eligible employees who turn 62, up to the age of 65.

We can withdraw our SRS monies over 10 years from the date of our first penalty-free withdrawal. Withdrawals are penalty-free only if they take place after the statutory retirement age that was prevailing at the time of our first SRS contribution. The statutory retirement age for all SRS members is currently at 62.

So, I can start to withdraw SRS monies at age 62 until age 71 without penalty. 
http://www.iras.gov.sg/irasHome/page04.aspx?id=1170

Updated on March 4, 2015
===================
It was announced on Budget Day 2015 that the cap of contribution of SRS will be increased by 20%.

The cap of contribution by Singaporean and Singapore PR will be raised from S$12,750 to S$15,300.

It will take effect on January 1st, 2016. The increment is S$2,550. Another good sum for tax relief ! The above table shall be updated based on S$15,300 contribution from year 2016 and onwards.

It will be good if SRS rules can be changed for the following:

(1) Give 1.5 or 2 times of tax relief instead of 1 to 1.

(2) Spread the withdrawal duration from 10 years to 15 years or 20 years. 10 years is too short and we might hit a little tax if our funds in SRS are doing tremendously well.

(3) Give better interest rate in SRS. 2.5% is a good start. :)

Friday, August 22, 2014

I Love Using Credit Cards (Revision 03)

Revision 03 (last paragraph): updated on August 28, 2014
Revision 02: updated on August 23, 2014

I am a big fan of credit cards. I once owned more than 20 credit cards but I have canceled some (due to zero chance of using them) and I still have about 15 credit cards with me. I get annoyed when there are so many articles, interviews, saying they hate using credit cards. They claimed it is bad to use future money. Credit is dangerous, etc. I have no clue what are they talking about, obviously nonsense.

Last Sunday "Me and My Money" article, this guy said he spent about S$4,000 to S$5,000 per month and he did not use credit cards. Oh dear, what a waste for a big spender like him. I will make sure every single cents go into my credit card expenses if they accept credit card. Let me share with you, what are credit cards mean to me.


Singapore credit cards are all free, unlike Malaysia credit cards, you have to pay RM 100 to use the second credit card. It is like a compulsary credit card fees. If you were in Malaysia, I would suggest you to minimize the quantity of your credit cards. In Singapore, banks reward you to sign up for credit card. Of course, it is not the FREE luggage that attract me to sign up for the credit cards although I have MANY free luggages from the banks. In good days, they even pay you FREE cash to sign up for credit cards. Maybank Singapore gave SGD100 free cash upon application, Standard Chartered and UOB gave SGD80 free cash upon application, etc.

Credit card is extremely good if one can control the expenses. There are people who have no control over their expenses, they just use credit card to "defer their payments". In that case, you better stop using it. Although Singapore credit cards impose annual fees charges (usually after second or third year of usage), what you need to do is to dial their 1800 toll-free number to request to waive the annual fees. My requests to waive the annual fees were 100% approved for the past 11 years in Singapore. There is no problem to waive the annual fees at all. One disadvantage to own too many credit cards is you can forget to make the payment. I did have 3 encounters of late payment and I was charged the late payment fees with interest! Thanks goodness, I got all of them waived. I was shocked that they waived the late payment charges too! I now make sure I remember to pay the bills. In short, I DO NOT pay annual fees or late payment fees for any Singapore credit cards, NEVER!

For frequent traveler, it is extremely good to own a right credit card especially if that is a business trip. I make sure all the charges are transacted with credit cards. The oversea hotel charges help me to accumulate spending really fast within a month. I wish I can use my credit card to pay for the business trip airfare! I love my current job and I have the privilege to choose to travel at least once in a month or not to travel at all if I don't feel like to.

As for now, the best Singapore credit card (for me) is UOB Signature VISA card. It gives 5% oversea cash reward! I use it all the time for my business trip until it reaches the cap of S$2,000 per month. Then, I will stop using it and use my second best Singapore credit card, UOB One card. It has quarterly cash reward up to 3.3% and additional 2% oversea spent cash reward up to S$5,000 per calendar year (S$100 cash rebate a year).

You just need to make sure all the tricks that the banks require. It is not difficult to meet the criteria.

UOB Signature VISA card: All oversea transaction must be made in local currency, not Singapore dollars. For example, if you swipe the card in Malaysia, make sure the transaction is in Ringgit and not Singapore Dollars. The monthly minimum foreign transaction must be at least S$1,000 in order to enjoy the 5% cash reward. The maximum cash reward they give you is 5% of S$2,000 per month, which means, you get FREE cash S$100 per month from UOB. I get this free cash all the time. Really damn shiok!

If you have a lot of oversea transactions (e.g. more than S$4,000), I recommend you to ask your spouse to apply for UOB Signature VISA card and you get the supplementary card from him/her and you swipe the supplementary card as well up to S$2,000 per month, you can get FREE cash of S$200 per month. :) You have two UOB Signature VISA card (one primary and one supplementary card). Shiok?

UOB One card: All you need to know is you need to make MINIMUM 3 transaction per month, and CONSISTENTLY for 3 months for more than S$300 spents, then you will be rewarded S$30 cash in quarterly basis. Of course they have higher tier of S$800 and S$1,500 per month (cash reward of S$80 and S$150 in quarterly basis). In additon, you get 2% oversea spent cash reward up to S$100 per year (cap at total S$5,000 oversea spent per calendar year). Maybank recently launched a similar credit card, or I would say exactly the same feature as UOB One card, totally the same cash rebate percentage (3.3%) with NO MINIMUM transaction required per month. That can be a good alternative but I have too many credit cards, ha ha.. I do not have that Maybank credit card. I am thinking to get one.

I have a habit to put all my travel photos, expenses claim report nicely in one folder for each business trip and I just realized I had 48x business trips for the past 4 years (almost once per month), that exclude my personal vacation trips. :)


Beside the best two credit cards (both from UOB bank) I mention above, I also use the following Singapore credit cards very often.

(1) Citibank Dividend Card. It is because of 10% cash reward of Starbucks. In every business trip, I enjoy my breakfast and tea break at Starbucks at Changi airport. That is why I don't go to Starbucks elsewhere in Singapore (sianz liao la ! ). Ha ha. Citibank had great GSS promotion in year 2013 May, June and July for 3 months. They as well gave 5% cash reward for oversea spent, with minimum spent of S$1,200 per month up to S$2,000 spent per month. Same great deal as UOB Signature VISA card. This dividend card gives 0.5% cash rebate for all spent but Citibank rewards you only when the cash rebate amount accumulated to S$50. Take note on this. Many people do not aware of this. It is like you have to spent a total of S$10,000 in order to get your cash rebate of S$50. But my savings in Starbucks (10% cash rebate) easily more than S$50 by now. 

(2) POSB Everyday Card. I use it for 20.9% discount on SPC fuel (bundle with the SPC member card). This is the highest fuel rebate in Singapore, of course I take it. I also use this card for my SP Power utilities bill payment through GIRO to enjoy 1% cash rebate. I pay HDB car park monthly fees using this card as well to enjoy 1% cash rebate (used to be 3% cash rebate! ). That's all the Everyday card for.

(3) OCBC Robinsons Card. I love Robinsons store. I am very happy that they now have Robionsons store at JEM, Jurong East, just a stone throw from my house! I love their in-store purchase cash rebate, member private sale events, etc. That is why I have the card and I don't need to go to Orchard anymore. Woo hoo !

(4) OCBC 365 Card. They give 6%  and 3% cash rebate when you dine locally on weekend and weekday (oversea dining too). There are some rules and I have yet to strategize and materialize the benefits. I have the card but I need to do some homework in order to hit the minimum spent of S$600 per month. I will share more next time about this card if I manage to reap the benefits.

Many of the time when my oversea spent at UOB Signature card is accumulated to say S$800 only, that's this month, August, example shown below (S$200 more in order to hit the minimum spent of S$1,000 per month), I will just make a visit to AEON at Bukit Indah, Nusajaya, Johor to have shopping spree on milk powders (biggest saving!), diapers, petrol, etc. (NOT FACIAL, FOOT MASSAGE or FREE LAUNDRY? NO, THANK YOU.) That easily helps me to have the minimum spent of S$1,000 and I get all the 5% cash reward. Hey, it is 50% cheaper for the milk powder in Malaysia too!

You do not need to make multiple trips into Johor (who ask you to pay custom fees, VEP all the time?). You just need to make ONE TRIP and get enough inventory for 10 months supply. Why not? The baby milk powder expiry date usually last for 2 years and your kid will consume them all within a year. Typically for me, one Nusajaya trip helps to save at least S$500. Not bad indeed. :) 

Singapore credit cards grant me 4 digits cash reward every year.
Why don't you love using Singapore credit cards?


Refer to my blog written in May 2012 too, "Who Say Credit Card is Not Good?".


Updated on August 23, 2014
====================
Yes, 90% of my oversea spents are business trips related, hence, they are all claimable from the company. When I joined the company, they immediately issued me a corporate American Express Card. After I know I got zero benefits of owning such corporate credit card, I canceled it.

Guess what, the company is paying annual fees to issue me such corporate American Express Card and there is no reward point system at all for the corporate credit card. What is the point to own a corporate credit card then?

The only benefit of owning such corporate credit card I can think of now is you DO NOT have to pay a single cent out from your own pocket. The company will pay the credit card bills on behalf of you. Well, I do not mind to pay the credit card bills myself first and claim it from the company as my company is able to refund the expenses claim within 30 days. I am fine with that. To make it worse, in Malaysia, particularly at Penang, the merchant stores don't really like American Express card, they still prefer VISA !

So, throw away your corporate credit card and own one beautiful UOB Signature VISA card! (UOB bank should pay me referral fees from now, don't you think so?)

Updated on August 28, 2014
====================
Biggest SCAM ever!

I suddenly realized my cash reward points down to S$17 when I am making a payment for my Citibank Dividend Card. I remember clearly I have definitely more points than this. I made a phone call to Citibank and guess what? They told me the cash reward points will be expired exactly 1 year and 3 months time. WHAT? This is not mentioned anywhere! The worst thing is, Citibank only rewards you the cash reward points after you have accumulated up to S$50 (that's quite a big mark to hit !).

Surprisingly, the Citibank officer immediately told me that he can reimburse those expired points to me and it well passes S$50 this time, total 56 reward points. So, in my next billing cycle, a cash reward of S$50 will be granted. How nice is this Citibank officer? The bill statement immediately updated after I hang up the call. That is really efficiency!

For those who owns this Citibank Dividend Card, most likely you have forfeited many reward points after the 15 months expiry date. Go and check it out!


Too bad, I will NOT recommend Citibank Dividend card anymore. I will only use it for 10% Starbucks instant cash rebate (not the same as rewards points). Bye Bye , Citibank Dividend Card.


UOB bank is still the BEST!

FREE cash from UOB ONE card. :)


In short, the BEST Credit Card in Singapore is the following (my choice):

(1) UOB SIGNATURE VISA - 5% Oversea Cashback
(2) UOB ONE VISA - 3.33%  Local spent Cashback + 2% Oversea Cashback
(3) MAYBANK PLATINUM VISA - 3.33% Local spent Cashback + 3% Oversea Cashback (until Dec 2014 only)
(4) STANDARD CHARTERED MANHATTAN - up to 3% local spent Cashback.
(5) CITIBANK DIVIDEND VISA - 10% Starbucks Cashback 
(6) POSB EVERYDAY MASTERCARD - 6% SPC fuel Cashback (on top of 17% SPC U Card discount).
(7) OCBC 365 VISA - 6% local dining Cashback on weekend and 3% local dining Cashback on weekday. Oversea dining Cashback 3%. Singtel/Starhub/M1 - Cashback 3%.
(8) CIMB INFINITE VISA - 1% local spent Cashback, 2% Oversea Cashback

I used the above 8 credit cards frequently. Please refer to their individual credit card Terms and Conditions in order to enjoy such Cashback percentage stated above.

For Singapore Credit Cards, go for Cashback feature. It is the best. Do not accumulate points to redeem vouchers. It is not worth it. Cash back percentage (3 to 5%) is so much higher than than voucher redemptions (usually only 0.2 to 0.3% of your total spent amount). 

p/s: yet to explore the new CIMB SIGNATURE VISA. 

Our CPF at the maximum ...

A Singaporean household of 3. 2 working adults, age 46 (1980s) and 1 young adult age 14. Voluntary Housing Refund (VHR) all monies back to C...